Tilray's Cash-Over-Debt Pitch Meets a Skeptical Market Test
A Globe and Mail analysis spotlights Tilray's net-cash position and 71% European growth, but the buy case rests on what the headline numbers leave out.
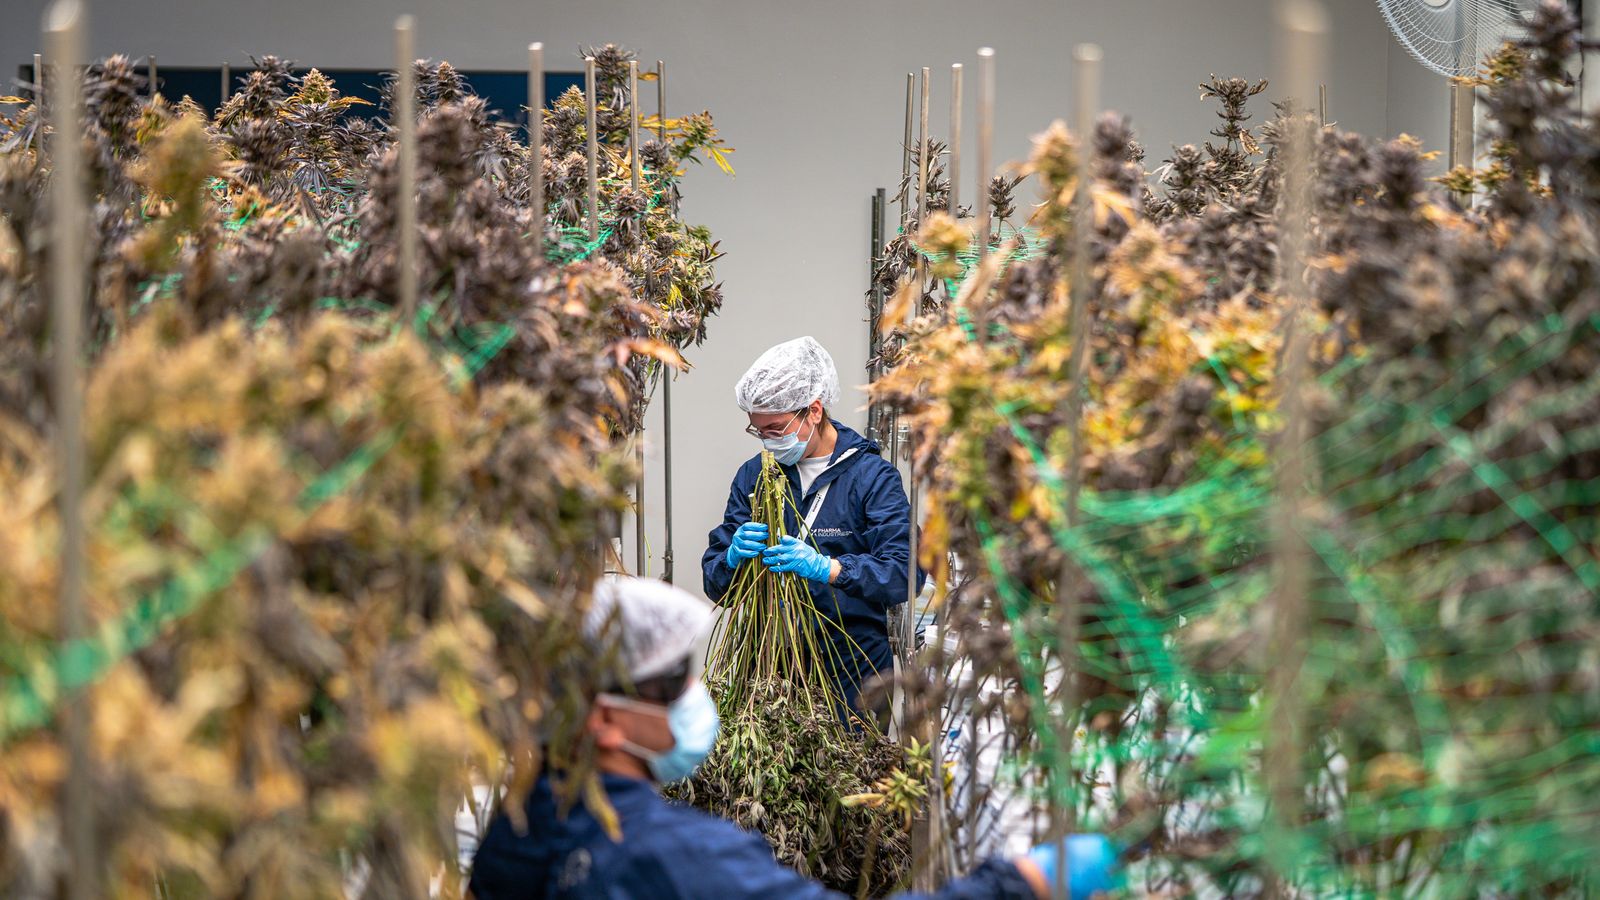
Workers in protective gear handling cannabis plants in an indoor facility.
The Globe and Mail frames Tilray as a balance-sheet survivor
The Nov. 20 Globe and Mail piece rests on two data points: cash exceeding debt and 71% growth in Europe.
Both claims come from the headline of the analysis, and the underlying filings were not included in the signal CannIntel reviewed. Treat the figures as the publication's framing until they're checked against Tilray's own reports.
The pitch is simple. In a sector where debt loads sank Canopy Growth's equity story and forced restructurings across the MSO tier, a licensed producer with net cash looks like a different animal. That's a real distinction. It's also a low bar.
My read: net cash is a floor, not a thesis
A clean balance sheet buys time, but time only matters if the operating business is heading somewhere.
Cannabis investors have been burned repeatedly by the 'we have runway' argument. Runway is what you talk about when the growth story is thin. The better question is what Tilray does with the cash: buy back stock, acquire, or fund losses.
How the company counts net cash matters too. Convertible notes, lease obligations and restricted cash can swing the headline. Check the debt definition before you accept the comparison.
The 71% European number deserves a denominator
Growth of 71% in Europe is meaningful only relative to how large the European segment is inside Tilray's total revenue.
Europe is the most compelling growth market in global cannabis right now. Germany's regulatory shift opened a medical import channel that Canadian licensed producers were built to serve, and Tilray has been among the more aggressive operators there through its European medical cannabis distribution footprint.
Still, a 71% jump off a modest base is arithmetic, not momentum. If Europe is a small slice of consolidated sales, it won't offset softness in Canadian adult-use pricing or the beverage and wellness segments. Without the segment revenue figure, the percentage is incomplete.
What the bull case has to clear
Three tests separate a defensible buy from a story stock.
- Whether consolidated gross margin is expanding as Europe scales, since medical product carries better pricing than Canadian recreational flower.
- Whether share dilution from past equity and convertible activity is outrunning per-share earnings improvement.
- Whether cash is rising from operations rather than from financing or asset sales.
Fail any one, and the net-cash headline starts to look like a one-time cleanup rather than a durable edge. Pass all three and the argument gets serious.
The competitive angle: Tilray versus the U.S. MSO field
Tilray's relative appeal is partly a function of how unappealing the alternatives look on leverage.
U.S. multistate operators carry heavy debt, and many are still working around 280E tax burdens that crush cash flow. Rescheduling to Schedule III would relieve the 280E problem for plant-touching U.S. operators. Tilray's U.S. business, though, is heavily weighted toward beverages and Tilray-owned craft brands rather than THC retail, which makes it a weaker direct beneficiary of rescheduling than its MSO peers.
Here's the tension. The thing that insulates Tilray from U.S. plant-touching risk also limits its upside if federal reform accelerates. You're buying a diversified, internationally weighted operator, not a rescheduling trade.
What to do with this
Treat the Globe and Mail piece as a screening input, not a verdict.
Pull Tilray's most recent quarterly filing. Confirm the cash and debt figures, the European segment's share of revenue, and the trend in adjusted EBITDA. The next real checkpoint is Tilray's upcoming quarterly report, where the European growth rate and cash position either hold or don't. Until then, the stock is a conditional yes, with the conditions doing most of the work.
Sources
The cannabis newsletter you forward to your team.
Federal policy, market data, grower alerts, and the one story that matters today. Sent every weekday at 7am. Free.
No spam. Unsubscribe with one click. 21+ only.
Related from Business

Provenance Pitch Tests Whether Shoppers Pay More for Flower
Origin claims, certification and protected regional names promise growers an escape from THC-percentage pricing, but the premium depends on shopper behavior, not branding.

Terrabis Opens Drive-Thru Dispensary in Mundelein, Illinois
Terrabis added a drive-thru lane to its Mundelein, Illinois dispensary, a convenience play that tests how far format can stand in for price in a crowded Chicago-area market.

Operator Bulletin: California Checkout Rules, Metrc, Hemp Insurance
California retailers face new checkout duties, Minnesota operators get Metrc deadlines, a cannabis contract ruling stands, and USDA updates hemp crop insurance.
More from the newsroom

Challenges to DEA Medical Marijuana Enforcement Ramp Up
Law360 reports a growing wave of legal challenges to DEA enforcement against medical marijuana, adding pressure on a federal posture already in flux.

Virginia Retail Cannabis Rollout Draws Industry Pushback as CCA Preps
Outlaw Report coverage shows Virginia's Cannabis Control Authority preparing for a regulated retail launch while operators push back on the rollout's design.

Texas A&M Scientists Develop Hemp Plant With No Detectable THC
Researchers report a hemp line with no detectable THC or other cannabinoids, a genetics milestone that could reshape fiber and grain production and the compliance math growers live by.